The rapid expansion of cryptocurrencies and blockchain technology could fundamentally reshape the global financial system. According to American financial analyst Tom Lee, much of the traditional financial infrastructure still relies on outdated technologies, while banks may be underestimating the speed at which digital assets could become integrated into mainstream financial services. This transformation raises important questions about the future competitiveness of banking institutions and their ability to adapt to accelerating technological change.
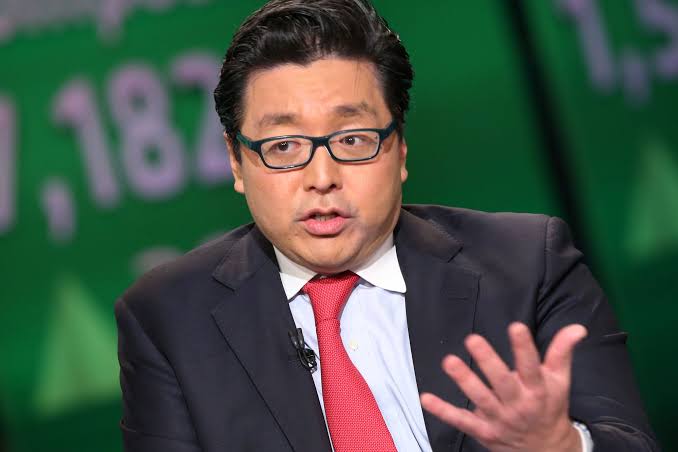
The global financial sector appears to be entering a new phase of technological transformation, driven by the growing adoption of cryptocurrencies and the expansion of blockchain-based financial applications. Against this backdrop, Tom Lee, financial analyst and co-founder of Fundstrat Global Advisors, warns that traditional banks could lose part of their competitive advantage if they fail to develop strategies capable of responding to the structural changes reshaping financial markets.
According to statements attributed to him, approximately 99% of financial activities still operate on outdated technological infrastructure. However, this figure is not supported, in the information currently available, by a verifiable statistical study or a publicly disclosed methodology. It should therefore be regarded as the analyst’s personal assessment rather than an established statistical fact.
Beyond the accuracy of this percentage, Lee’s remarks raise a fundamental strategic question: are traditional banking institutions sufficiently prepared to respond to the accelerating pace of technological transformation, particularly as new models of payments, international transfers, and digital asset management continue to emerge?
Blockchain and Banking: Towards a Restructuring of the Global Financial System.
Blockchain technology is opening new opportunities for financial services, particularly in cross-border payments, asset tokenization, interbank settlements, and the automation of financial transactions. Some of its applications could also help reduce transaction processing times, improve transparency, and increase the efficiency of payment infrastructure.
Stablecoins and tokenized bank deposits are emerging as potentially significant innovations in the modernization of cross-border financial services, offering new solutions for transaction settlement and liquidity management.
Nevertheless, the widespread adoption of these technologies remains subject to major regulatory and security challenges, including consumer protection, cybersecurity, anti-money laundering compliance, and interoperability between traditional financial systems and emerging digital platforms.
For banking institutions, the central challenge is not necessarily to replace existing financial infrastructure with cryptocurrencies, but rather to identify areas where these innovations can generate measurable economic value through improved operational efficiency, lower transaction costs, and more flexible financial services.
Banks that successfully implement well-structured digital transformation strategies could strengthen their competitive positions and attract new customer segments, particularly in markets experiencing sustained growth in digital financial services.
Conversely, the premature adoption of immature or insufficiently regulated technologies could expose financial institutions to additional operational, legal, and financial risks.
From this perspective, the transformation described by Tom Lee should not be interpreted as an inevitable outcome or a development that will unfold according to a predetermined timetable. Instead, it represents a strategic scenario whose potential implications deserve careful examination by banks, regulators, and other financial market participants.
The debate also highlights a broader structural challenge facing the banking industry: how to modernize legacy infrastructure while preserving financial stability, regulatory compliance, and public confidence.
As digital assets and blockchain-based financial solutions continue to evolve, the relationship between traditional banking institutions and emerging financial technologies could increasingly shift from competition towards integration and cooperation.
The central challenge for global finance will be to strike the right balance between technological innovation, financial stability, and consumer trust. In this context, the future of banking may depend less on a direct confrontation between banks and cryptocurrencies than on the ability of financial institutions to integrate emerging technologies and build a more efficient, secure, and interconnected financial system.